
Insights for work and life.
Foreign Founder Contributing IP Before Relocation: Contract, Tax and Pass Sequence
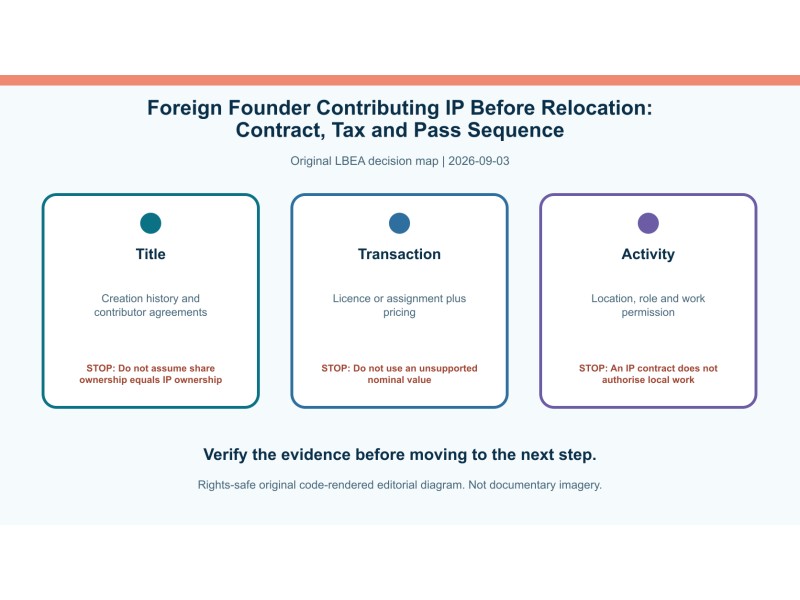
Answer first. A Singapore company may need a documented right to use founder-owned IP, but that contract does not authorise the foreign founder to work in Singapore or prove tax treatment.
Related reading: resident director and founder sequence and foreign founder pay sequence.
Identify the asset and owner
List the code, brand, domain, design, data, know-how or other intangible the business needs. Record who created it, under which contract, when, and whether third-party material is embedded. Share ownership, directorship and IP ownership are separate. Do not state that incorporation automatically moved the founder’s pre-existing IP to the Singapore company. Preserve source files, registrations, assignments and contributor agreements for review.
Choose licence or transfer deliberately
A licence can define scope, territory, term, exclusivity, sublicensing, improvements and termination. An assignment changes ownership and needs appropriate execution and schedules. The choice affects control, valuation, tax, financing and exit diligence. Do not use a one-line board minute to paper over uncertain title. The company and founder should obtain legal and tax advice before implementation, especially where multiple jurisdictions or investors are involved.
Price the related-party arrangement
IRAS describes transfer pricing as pricing between related parties and specifically includes the use or transfer of intangibles. Apply the arm’s-length principle based on functions, assets and risks, and keep contemporaneous support where required. A nominal fee, free use or large royalty is not automatically correct because the founder controls both sides. Separate the valuation method, payment terms, withholding questions and accounting entries.
Keep board oversight real
The Singapore board should receive the agreement, ownership evidence, valuation basis, conflicts disclosure, business rationale and cash-flow effect. ACRA says director duties apply to all directors. Record deliberation and abstention where appropriate. Do not ask a resident or nominee director to sign without information. Ensure the company can actually comply with the licence and that its public statements do not overstate ownership.
Separate overseas contribution from Singapore work
MOM says a non-resident foreigner needs no EP merely to be registered as a director. That narrow statement does not authorise the founder to operate from Singapore. Map where development, negotiation, management and support occur. Before the founder relocates or performs local operational work, assess and obtain the appropriate permission. A signed IP agreement is not a work pass and incorporation does not guarantee one.
Worked example
A founder owns software written before incorporation. The Singapore company needs it for customer delivery. Counsel confirms title, the parties choose a defined licence, tax advisers document the related-party price and the board records conflicts and rationale. An employed local team supports customers. The founder continues approved overseas activities and does not start working from Singapore until the relevant immigration and employment sequence is complete.
Create the closing file
Keep the IP schedule, chain of title, third-party consents, signed agreement, valuation, transfer-pricing analysis, board minutes, invoices and work-location record. Revisit the arrangement when functions, ownership, funding or residence change. Distinguish company registration, contract validity, tax treatment, director duty, work permission and future PR or citizenship. None of them supplies an automatic answer for the others.
How to use this guide
Start with the reader, decision and evidence identified above. Write the next action and owner beside every unresolved point, then set a review date. Keep authority-issued records unchanged and preserve earlier versions when a correction is made. If a fact, document or deadline does not fit the matrix, pause instead of forcing it into the nearest category. Official guidance can change, and a checklist cannot decide disputed facts or replace advice on a specific case. The strongest file shows what was known, when it was known, which source controlled the step and why the chosen action followed. Record every unresolved assumption, identify who can verify it, and never treat silence or a pending application as approval.
Decision and evidence matrix
| Checkpoint | Evidence to verify | Stop condition |
|---|---|---|
| Title | Creation history and contributor agreements | Do not assume share ownership equals IP ownership |
| Transaction | Licence or assignment plus pricing | Do not use an unsupported nominal value |
| Activity | Location, role and work permission | An IP contract does not authorise local work |
Primary sources checked for this guide
Source status was checked on 3 September 2026. Reopen the controlling page before acting because procedures and legal status can change.
- Inland Revenue Authority of Singapore: Transfer Pricing, supporting Related-party transactions, including use or transfer of intangibles, should follow the arm’s-length principle and may require contemporaneous documentation.
- Ministry of Manpower: Is a foreigner required to apply for an EP if registered as a director but not resident?, supporting A foreigner not residing in Singapore does not need an EP merely to be a registered director.
- Accounting and Corporate Regulatory Authority: Company directors’ duties and key obligations, supporting All directors, including nominee and non-executive directors, remain responsible for statutory duties and company records.
Authority and relationship disclosure. Little Big Employment Agency Pte. Ltd. is not affiliated with or endorsed by MOM, ICA, ACRA, MAS or IRAS. Contacting LBEA does not create a solicitor-client relationship.
Real people. Right here in Singapore.