
Insights for work and life.
Paying a Foreign Founder: Sequence Salary, Director’s Fees and Work Permission
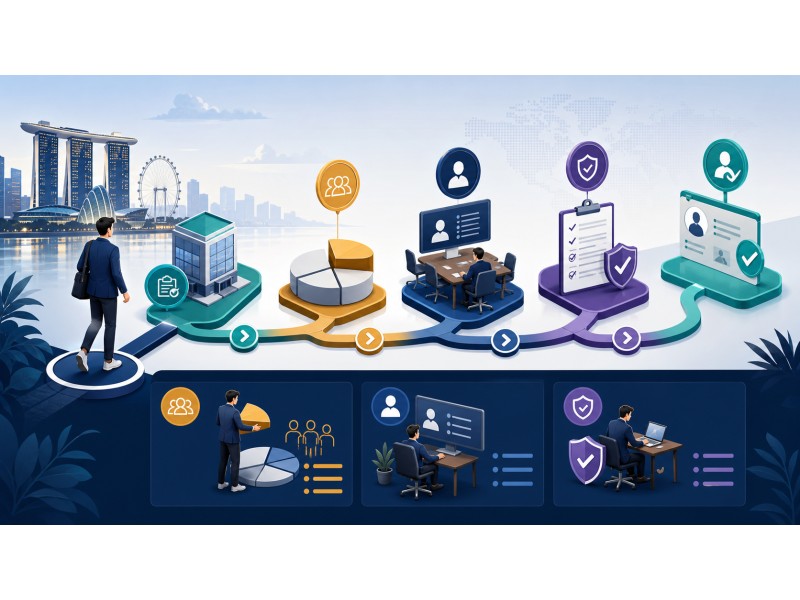
Quick answer. Incorporation and share ownership do not answer when a foreign founder may work or how the company should record pay. This matrix separates each capacity and approval.
Related reading: founder work-pass sequence and EP holder and directorship guide.
Separate the founder’s four capacities
A foreign founder may be a shareholder, board director, employee and service provider, but those labels do not automatically arise together. Share ownership can produce dividends. Board service can produce director’s fees. Operational work under a contract of service can produce salary. Genuine external services may be invoiced under a separate arrangement. For each payment, record the capacity, approving body, service period, work location, tax treatment and immigration basis. Do not rename salary as a dividend or fee to avoid a work-permission question.
The sequencing matrix
Before incorporation, define who will own shares and who will operate the business. At incorporation, satisfy ACRA’s resident-director and officer requirements without treating a corporate title as work authorisation. Before the founder performs day-to-day Singapore work, identify and obtain the status that permits the actual role. Only then should employment payroll start for Singapore services. Board fees and shareholder distributions follow their own corporate approvals and tax records. Each stage needs a dated evidence file.
Salary is evidence of an employee role
A founder salary should match a genuine job description, employment contract, board approval, payroll capacity and the work-pass representation. The company should be able to show what work is performed, for whom and from where. Paying a salary before the founder is authorised to perform the Singapore role can create an immigration problem rather than solve an eligibility test. Conversely, leaving a genuine employee off payroll can create inconsistent tax, accounting and pass records.
Director’s fees are not a universal substitute
Director’s fees compensate board service and follow corporate approval and tax timing. IRAS explains that entitlement commonly depends on when fees are approved and whether services have been rendered. An executive founder who manages staff and delivers company work cannot assume that calling every payment a director’s fee removes the employment character or the need for work permission. Keep board minutes, service scope, approval date and tax treatment separate from employment payroll.
Dividends and shareholder returns
A dividend is a return on share ownership, not wages for work. It requires the relevant corporate basis and records and should not be calculated as a disguised monthly salary. A pre-revenue company should not promise distributions disconnected from lawful profits or approvals. The immigration question remains factual: is the founder performing work in Singapore? Passive ownership and operational management are different. Obtain corporate and tax advice before designing a mixed remuneration package.
Worked scenario
A foreign founder incorporates through a corporate service provider, owns most shares and appoints a resident director. While overseas, the founder prepares investor materials and receives no Singapore payroll. After a suitable pass is issued for a genuine Singapore role, the board approves the employment contract and payroll starts on the authorised date. Later, members approve a director’s fee for board service, recorded separately. A dividend is considered only when the company has a proper basis. The files never imply that incorporation itself authorised work.
Release checklist
Before any founder payment, identify capacity, approving document, service location, work-authorisation status, effective date, payroll or withholding treatment and financial-statement classification. Compare the records across ACRA, MOM, IRAS, employment contract and bank narration. Stop if one system calls the person passive while another shows active management. A corporate-services provider can help with establishment records, but incorporation never guarantees a work pass, PR or citizenship. Specific legal, tax and immigration advice may be necessary.
Decision and evidence matrix
| Checkpoint | Evidence to verify | Stop condition |
|---|---|---|
| Shareholder return | Lawful dividend basis and records | Not wages for operational work |
| Board service | Corporate approval and service period | Tax treatment does not create work permission |
| Employment | Contract, salary, payroll and pass facts | Do not start Singapore work prematurely |
| External service | Real scope, payer and work location | Do not relabel employee duties |
Primary sources checked for this guide
The legal and administrative status of each source was checked on 29 August 2026. Readers should reopen the controlling page before acting because procedures and eligibility rules can change.
- Accounting and Corporate Regulatory Authority: Understanding requirements and eligibility, supporting Foreigners can own Singapore businesses but a person moving to Singapore to run one needs the appropriate work pass; local-residency requirements also apply.
- Ministry of Manpower: EntrePass eligibility, supporting EntrePass is for qualifying venture-backed or innovative businesses and has specific company, shareholding and applicant criteria.
- Inland Revenue Authority of Singapore: Employment income: salary, bonus and director’s fee, supporting Salary and director’s fees are distinct taxable receipts with different entitlement timing and record considerations.
- Singapore Statutes Online: Companies Act 1967, supporting Section 169 governs member approval of emoluments for directors in specified offices, while section 403 restricts dividends to profits.
Authority and relationship disclosure. Little Big Employment Agency Pte. Ltd. is not affiliated with or endorsed by MOM, ICA, ACRA, MAS or IRAS. Contacting LBEA does not create a solicitor-client relationship.
Real people. Right here in Singapore.