
Insights for work and life.
Can a Family Member Count as an Investment Professional for 13O or 13U?
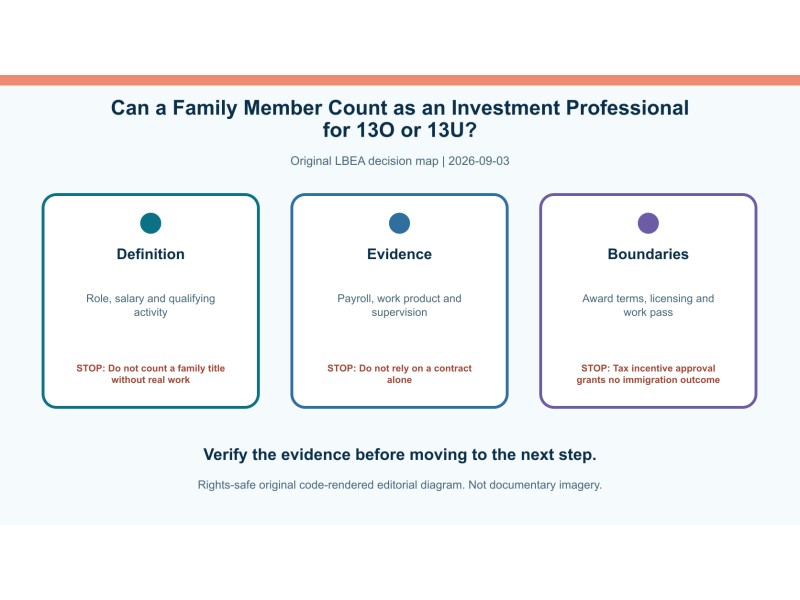
Answer first. A family relationship does not by itself disqualify or qualify a person. The fund and manager must test the current incentive definition, real work, remuneration, governance and pass status.
Related reading: family-office payroll reconciliation and 13O and 13U annual declarations.
Start with the exact scheme and award
Identify whether the fund relies on section 13O or 13U, the application date, award terms, fund manager and current financial year. Do not apply a headline from an older article or another structure. Read the MAS approval and current material. The investment-professional condition is only one part of a wider set of fund-size, management, spending, investment and reporting requirements.
Test the role, not the surname
MAS material describes investment professionals as portfolio managers, research analysts and traders who earn more than S$3,500 per month and engage substantially in qualifying activity. Build a duty map showing decisions, research, execution, monitoring and time allocation. A family title, board seat or occasional meeting does not prove the role. Conversely, a genuine family member should not be rejected solely because of the relationship.
Verify remuneration and payroll
Record contractual salary, payment dates, bank credits, payroll ledger and tax reporting. The current definition uses a salary threshold, but satisfying it does not prove substantial qualifying activity. Related-party remuneration also needs a defensible commercial basis. Separate salary, director fees, distributions and investment returns. Do not recycle the same payment across entities or describe unpaid family assistance as salaried headcount.
Manage conflicts and supervision
Define reporting lines, authority limits, personal-account dealing controls, investment committee records and conflicts procedures. Family influence can make an evidence trail more important, not less. Ensure the fund manager can supervise and evaluate work and that the individual does not approve personal remuneration without proper governance. Keep attendance and work product proportionate to the claim that the person is substantially engaged.
Check work permission independently
MOM states that foreigners intending to work in Singapore need a valid pass. A 13O or 13U structure, family ownership or MAS tax-incentive approval does not create work permission. Map employer, role, location, salary and start date to the applicable pass process. Do not begin Singapore work while an application is pending or imply that tax-incentive headcount guarantees a pass, PR or citizenship.
Worked example
An adult family member is hired as a research analyst by the Singapore fund manager. The file contains a real job description, market pay analysis, valid work permission, research outputs, investment-committee participation and controlled conflicts. Payroll and tax records match the contract. The family office counts the person only after advisers confirm the current award and scheme treatment. A sibling who attends quarterly family meetings is not counted merely for being involved.
Build quarterly evidence
Each quarter, reconcile headcount, contracts, salary, bank payment, work product, time allocation, pass status, fund-manager employment and annual-declaration data. Investigate gaps before year end. Obtain Singapore tax, regulatory, legal and immigration advice for the actual structure. This checklist does not decide incentive eligibility or licensing and makes no representation about approval, PR or citizenship outcomes.
How to use this guide
Start with the reader, decision and evidence identified above. Write the next action and owner beside every unresolved point, then set a review date. Keep authority-issued records unchanged and preserve earlier versions when a correction is made. If a fact, document or deadline does not fit the matrix, pause instead of forcing it into the nearest category. Official guidance can change, and a checklist cannot decide disputed facts or replace advice on a specific case. The strongest file shows what was known, when it was known, which source controlled the step and why the chosen action followed. Record every unresolved assumption, identify who can verify it, and never treat silence or a pending application as approval.
Decision and evidence matrix
| Checkpoint | Evidence to verify | Stop condition |
|---|---|---|
| Definition | Role, salary and qualifying activity | Do not count a family title without real work |
| Evidence | Payroll, work product and supervision | Do not rely on a contract alone |
| Boundaries | Award terms, licensing and work pass | Tax incentive approval grants no immigration outcome |
Primary sources checked for this guide
Source status was checked on 3 September 2026. Reopen the controlling page before acting because procedures and legal status can change.
- Monetary Authority of Singapore: MAS 13O and 13U scheme conditions, supporting The current material defines investment professionals by role, salary above S$3,500 and substantial engagement in qualifying activity, with scheme-specific headcount conditions.
- Inland Revenue Authority of Singapore: Transfer Pricing, supporting Related-party remuneration and services require arm’s-length analysis and contemporaneous documentation where applicable.
- Ministry of Manpower: Work passes, supporting Foreigners who intend to work in Singapore must have a valid pass before starting work.
Authority and relationship disclosure. Little Big Employment Agency Pte. Ltd. is not affiliated with or endorsed by MOM, ICA, ACRA, MAS or IRAS. Contacting LBEA does not create a solicitor-client relationship.
Real people. Right here in Singapore.